ether.fi
ether.fi is a crypto‑native neobank on Ethereum that combines non‑custodial staking, automated yield and strategy vaults, and payment functionality in a single application, allowing users to save, grow, and spend crypto in one connected experience that includes staking ETH, deploying assets across decentralized finance (DeFi), accessing fiat on‑ and off‑ramps for global transfers, and paying for everyday goods with a linked payment card. The project was founded by Mike Silagadze and Rok Kopp in 2022.[1]
As of April 2026, ether.fi managed more than 2.8 million staked ETH, worth roughly $6.5 billion at that time, and had around 300,000 accounts and 70,000 active Cash cards.[20]
Overview
Ether.fi is a decentralized staking and DeFi protocol structured so that users retain control over their staked ETH and related receipt tokens across its Stake, Liquid, and Cash product lines.[8] In its own documentation and blog, ether.fi describes itself as a crypto neobank that combines staking, yield vaults, and payments into a single non‑custodial app, with Stake, Liquid, and Cash identified as the main user‑facing product pillars on the docs home page.[14] Users deposit ETH (and, in newer products, BTC and USD) into a Liquidity Pool. From this pool the protocol creates validators that are operated by node‑operator clusters using Distributed Validator Technology, rather than by individual solo stakers managing their own validator keys. This pooled model issues eETH and weETH as liquid staking receipts on top of the Liquidity Pool and underpins automated DeFi strategies and spending products.[1]
Ecosystem
Ether.fi’s ecosystem spans node operators participating in DVT clusters, DeFi protocols integrating eETH and weETH as collateral, and partners in areas such as oracles, security, and restaking. From 2025 to 2026 the protocol adopted a more conservative restaking risk posture, increasing the share of assets held in non‑restaked positions, avoiding allocations to slashable restaking protocols, and moving restaking exposure off weETH into a separate opt‑in token, weETHs, while winding down its EigenLayer positions.[9][10] Ether.fi’s security materials describe a four‑layer defense model—covering operational security, smart contracts, cross‑chain controls, and active defense—intended to limit the impact of failures in surrounding infrastructure such as bridges or external protocols.[15]
Solo Stakers
Ether.fi implements Distributed Validator Technology (DVT) as a core part of its staking design to enhance the security and resilience of validators within the Ethereum network. This technology enables solo node operators to participate in validator clusters distributed across multiple machines and locations, contributing to network decentralization and reducing reliance on centralized data centers.[4]
Within programs such as Operation Solo Staker, individual operators join DVT clusters built on middleware such as SSV Network and Obol, rather than posting their own 32 ETH bond.[4] Validators in these clusters are funded from ether.fi’s central LiquidityPool, and operators run protocol validators on behalf of pooled stakers, earning a share of staking rewards in exchange for meeting uptime, hardware, and operational standards.[4] Eligibility requirements focus on prior staking experience, reliable connectivity, and adherence to the program’s terms of service, with configuration details evolving over time as the solo‑staker and DVT programs mature.
Liquid
Liquid is a family of non‑custodial DeFi vaults that automate strategy selection and rebalancing across multiple protocols on behalf of users. Liquid vaults accept assets such as eETH, weETH, WETH, BTC, and USD‑denominated tokens and allocate them across integrated DeFi venues to seek risk‑adjusted yield without requiring users to manage positions directly. Ether.fi’s live Liquid vaults are built on two main architectures: Veda’s BoringVault framework for most on‑chain vaults, and Midas infrastructure for reserve‑style and real‑world‑asset (RWA) vaults. Together these reflect an increasing focus on ETH‑, BTC‑, USD‑, and RWA‑oriented strategies.[11][8] In June 2026, as part of this RWA push, ether.fi allocated $100 million exclusively into a Plume RWA Vault built on Plume Nest Vaults to provide institutional‑grade real‑world‑asset yield to ether.fi users, a collaboration described further in the Partnerships section.[21]
Cash
Cash is ether.fi’s crypto‑native credit card and payments product, integrated into the main application and portfolio alongside the Stake and Liquid product lines.[14][13] It combines a Visa credit card and mobile app linked to a user’s ether.fi account, allowing spending against on‑platform crypto balances while keeping underlying assets in non‑custodial smart‑contract vaults.[19] Through this integration, users can fund everyday purchases directly from their ether.fi portfolio without moving assets into a custodial intermediary. In the August 2026 “ether.fi Summer” release, launch coverage described the Cash experience as bundling tokenized stocks and metals, an integrated Aave V4 lending market using portfolio‑backed credit, automatic yield on idle stablecoins, and fiat on‑ and off‑ramps across about 70 currencies, with CEO Mike Silagadze framing these features as part of a broader non‑custodial crypto neobank strategy.[22]
Cash also allows users to borrow against their ether.fi assets, including DeFi positions, via a dedicated Aave market deployed as part of ether.fi’s “Summer” release on Optimism.[13][8] Credit lines are routed through this Aave deployment so that yield‑bearing positions held in the ether.fi ecosystem can serve as collateral while remaining on‑chain and non‑custodial. This structure aligns Cash with ether.fi’s broader revenue model, in which payments‑related income from card interchange, foreign‑exchange spreads, and interest on certain balances contributes to protocol revenue shared with ETHFI stakeholders.[8]
Key features of Cash include:
- Card spending through a Visa credit card linked to ether.fi balances, with cashback and rewards on purchases.
- Integrated fiat on‑ and off‑ramps in multiple currencies, supporting deposits and withdrawals between bank accounts and crypto holdings.
- Support for using yield‑bearing ether.fi and DeFi assets as collateral for borrowing, with credit routed through a dedicated Aave market while assets remain in smart‑contract vaults.[19][13]
Features
In the production ether.fi system, user deposits into the Stake product are directed to a LiquidityPool contract, which mints either eETH, a rebasing receipt token, or weETH, a non‑rebasing wrapped version, depending on the user’s choice.[1] The LiquidityPool allocates pooled ETH to validators operated by permissioned and community node‑operator clusters using Distributed Validator Technology, implemented via middleware such as SSV Network. It is responsible for validator creation and assignment, reward accounting, and redemptions.[1] When users redeem by burning eETH or weETH, the pool first serves withdrawals from available liquidity. If liquidity is insufficient, it queues validator exits and distributes ETH to claimants once withdrawals have finalized on the beacon chain and been received by the pool.[16][1]
Ether.fi describes its security posture as “non‑custodial, actively defended.” Protocol contracts are structured so they cannot unilaterally move user funds, while explicitly scoped defense powers allow designated administrators to pause affected contracts and block in‑flight attacks. These authorities are divided between upgrade‑focused and operations‑focused multisignature wallets.[15]
Delegated Staking
In ether.fi’s current design, delegation occurs through node‑operator and solo‑staker participation in Distributed Validator Technology clusters that run validators funded from the central LiquidityPool, rather than from each operator’s personal 32 ETH bond.[4] Approved node operators and solo stakers join DVT clusters built on middleware such as SSV Network and Obol, where they hold validator key shares, maintain hardware, and meet performance and reliability requirements in exchange for a share of staking rewards generated by the validators they help operate.[4] Validator assignment from the LiquidityPool to eligible operators is handled automatically by the protocol according to its allocation logic, so delegating users interact only with eETH and weETH, not with individual validator slots.[1] Earlier versions of ether.fi used an auction‑plus‑NFT design for delegation, which has since been replaced by the pooled DVT model.
Permissionless Withdrawals
Following the Shanghai and Capella upgrades on the Ethereum Execution and Consensus Layers and the introduction of EIP‑4895 withdrawals, ether.fi’s pooled model allows users to exit by burning eETH or weETH and redeeming ETH directly from the LiquidityPool, rather than managing per‑validator withdrawal contracts.[1] When a user requests a redemption, the LiquidityPool first fulfills the claim from available on‑chain liquidity. If liquidity is insufficient, the protocol queues validator exits, and once those exits finalize on the beacon chain the corresponding withdrawals are received into a pool‑level vault and become available for users to claim permissionlessly.[16] As part of the “Safe Staking, From Doctrine to Code” upgrade, ether.fi hard‑coded invariants that require finalized withdrawals to be escrowed on‑chain until claimed and to remain claimable even if protocol administrators pause other operations, so that repayment of user principal and rewards cannot be blocked.[16]
Rewards Skimming
Under the current pooled model, validator rewards accrue into the LiquidityPool and are reflected in the eETH rebase. Users receive their share of staking yield automatically, either through balance adjustments in eETH or, for weETH, through appreciation of the wrapped token’s value relative to ETH.[1] Users no longer interact with per‑validator “withdraw safe” contracts to skim rewards, as those mechanics are abstracted behind pool‑level accounting.
Full Withdrawal
In the pooled design, users perform full exits by redeeming and burning their eETH or weETH, receiving ETH once the LiquidityPool either serves the withdrawal from existing liquidity or, if necessary, completes protocol‑managed validator exits and processes the resulting finalized withdrawals.[16][1] Full validator exits and redistribution of funds are handled collectively by the protocol, rather than through user‑managed per‑validator withdraw‑safe contracts.
Sharing Protocol Revenue
Ether.fi’s protocol revenue is organized around three pillars: Stake, Liquid, and Cash.[8] Stake generates revenue primarily through protocol fees and spreads on staking yield earned by validators funded from the LiquidityPool. Liquid contributes management and performance fees on its automated DeFi vaults. Cash earns from payments‑related sources such as card interchange, foreign‑exchange spreads, and interest on certain balances, as ether.fi scales its neobank offering.[8] According to ether.fi’s “Building a $1B Revenue DeFi Protocol” update for 2025, the protocol targets directing up to approximately 25% of protocol revenue, conditional on profitability and governance decisions, toward ETHFI buybacks for the benefit of sETHFI holders, aligning token value accrual with usage of the Stake, Liquid, and Cash products.[8]
Tokens
ETHFI
The governance token ETHFI empowers community members to engage directly in ether.fi's development and ecosystem expansion. ETHFI holders can participate in key protocol decisions, including the launch of the ether.fi Grants Program, setting economic parameters, granting permissions to software developers, approving node operators, and engaging in token staking for additional incentives and treasury diversification efforts.[3] As ether.fi evolved into a broader crypto neobank spanning Stake, Liquid, and Cash, ETHFI also became the protocol’s primary value and membership layer. Governance directs a portion of protocol revenue—targeting up to 25% when profitable—toward buybacks and benefits for staked ETHFI holders tied to product‑level perks.[8]
Tokenomics
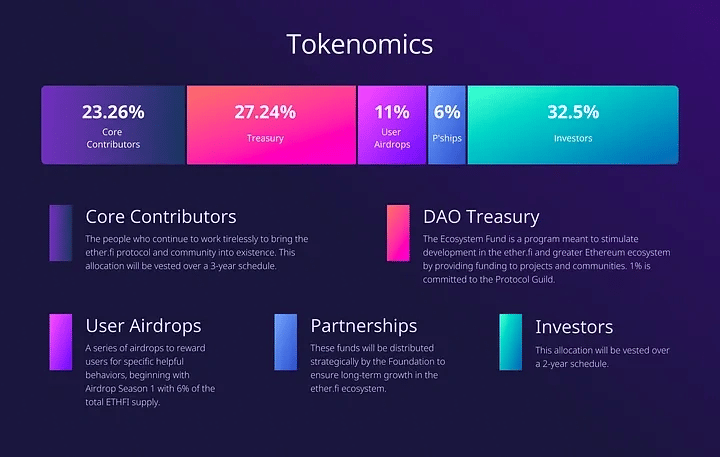
The allocation of resources within the ether.fi ecosystem is divided into several categories:[3]
- Core Contributors: 23.26%; Core Contributors consist of individuals actively developing and advancing the ether.fi protocol and community. Their allocation will be vested over three years to incentivize ongoing contributions.
- DAO Treasury: 27.24%; the DAO Treasury includes the Ecosystem Fund, which aims to foster development within the ether.fi and broader Ethereum ecosystem. A portion of this fund, 1%, is dedicated to the Protocol Guild.
- User Airdrops: 11%; User Airdrops are designed to reward users for specific beneficial actions. These airdrops commence with Airdrop Season 1, distributing 6% of the total ETHFI supply.
- Partnerships: 6%; Partnerships involve strategic distribution of funds by the Foundation to foster long‑term growth in the ether.fi ecosystem.
- Investors: 32.5%; Investors' allocation will be vested over two years.
Alongside this fixed token allocation, ether.fi’s later revenue model channels a share of income from the Stake, Liquid, and Cash product lines into ETHFI‑centric mechanisms such as buybacks and staked‑ETHFI rewards, aligning the token’s long‑term value with protocol revenue and usage.[8]
ether.fi Staked ETH (eETH)
ether.fi Staked (eETH) is a rebasing ERC-20 token introduced by ether.fi that represents a claim on pooled ETH held in the protocol’s Liquidity Pool and staked in the Ethereum Proof-of-Stake system.[1] When users deposit ETH via the Stake product, the Liquidity Pool mints eETH, and a rebasing mechanism automatically distributes staking rewards to eETH holders by adjusting balances across all addresses. The Liquidity Pool allocates ETH to validators run by node‑operator clusters using Distributed Validator Technology, while deposits and redemptions are serviced from pool liquidity, with full validator exits queued in the background as needed.[1]
weETH is a non‑rebasing wrapped version of eETH designed to serve as “clean” collateral across DeFi integrations, maintaining a stable balance while its value reflects the rebasing of the underlying eETH. In earlier iterations, eETH and weETH functioned as Liquid Restaking Tokens with default EigenLayer exposure, but ether.fi subsequently separated restaking from the core collateral token. As of August 2026, all restaking exposure has been removed from weETH, which now behaves as a traditional liquid staking token, while restaking is offered on an opt‑in basis through a separate token, weETHs, built on the Symbiotic protocol.[9][10] Ether.fi’s own slashing‑risk documentation cited in these reports states that less than 1% of assets remained restaked with EigenLayer by August 2026, with plans to reach zero restaked share in the third quarter of 2026 and to remove EigenPod withdrawal credentials from its validators by the fourth quarter of 2026.[9]
In 2026 ether.fi undertook a major protocol‑level security upgrade under the banner “Safe Staking, From Doctrine to Code,” recasting its design around three principles: non‑custodial by construction, safety enforced in code, and active defense.[12] The upgrade, audited by Certora, moved key safety guarantees into on‑chain invariants—for example, preventing eETH’s exchange rate from deflating, ensuring that weETH cannot be under‑backed relative to the eETH it wraps, and hard‑coding ceilings and circuit breakers for operations such as minting, burning, and withdrawal finalization. These properties are continuously stress‑tested via invariant testing, while an operational framework of tiered roles, guardian keys, and expiring pauses is intended to bound the impact of security incidents in time and scope.[12]
A dedicated weETH hardening program, undertaken with Steakhouse Financial, further tightened governance and contract‑level constraints around the wrapped token. This process extended governance timelocks, distributed upgrade authority across independent entities, bounded oracle reports, introduced deterministic and unpausable exit paths, and added protections such as a redemption fallback if the oracle fails and a cryptographic hard‑disable on new slashing exposure.[17] Following these changes, weETH earned an independent A+ risk rating from Credora and was admitted to Steakhouse Prime vaults with an 86% loan‑to‑value (LTV) ratio for weETH/USDC and weETH/USDT markets.[16][18]
Partnerships
Ether.fi has announced a series of partnerships with infrastructure providers as its validator, oracle, and restaking stack has evolved, with these collaborations representing specific integrations at the time rather than the full description of its present‑day LiquidityPool‑ and DVT‑based architecture.[14]
Obol Labs
On February 23, 2023, when ether.fi introduced its platform on X, Obol Labs announced itself as an official DVT partner. Obol Labs is a developer of Ethereum‑aligned Distributed Validator Middleware through the Obol Network and its ecosystem, and this collaboration formed part of ether.fi’s early DVT stack alongside other middleware providers.[5]
Aethos
On March 26th, 2024, ether.fi announced a partnership with Aethos, a decentralized smart contract engine, under which ether.fi uses Aethos’ AVS to provide an additional layer of protocol security.[6] This arrangement is one component of ether.fi’s broader security and risk‑management stack described elsewhere in its documentation.
Redstone Oracles
On April 12th, 2024, ether.fi partnered with RedStone Oracles in a $500 million restaking arrangement to secure data oracles, utilizing over 20,000 node operators and eETH tokens to help protect against certain network vulnerabilities at that time.[7] This partnership reflects ether.fi’s 2024 restaking strategy and sits alongside later changes to its restaking and risk posture documented in the core protocol materials.
ETHGas
In April 2026, ether.fi committed $3 billion worth of ETH as “validator liquidity” to ETHGas, a marketplace for Ethereum blockspace futures, over a three‑year period.[20] According to reporting at the time, this liquidity was to be sourced from more than 2.8 million ETH that ether.fi had under management and deployed into ETHGas, which is designed to let validators sell blockspace commitments in advance for more predictable yields and execution while supporting institutional demand for Ethereum blockspace.[20]
Plume
In June 2026, ether.fi and Plume announced a flagship RWA Vault integration under which ether.fi allocated $100 million exclusively into a Plume RWA Vault built on Plume Nest Vaults.[21] The partnership was intended to give eligible ether.fi users access to institutional‑grade real‑world‑asset yield from standardized onchain vaults and formed part of ether.fi’s broader strategy to offer RWA and institutional‑focused yield products.[21]